核心要点
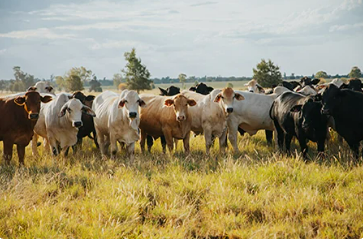
澳大利亚大范围地区持续降雨,促使养殖户选择留存牲畜。
加工牛价格指数持续创下新高。
肉牛屠宰量有所下降,主要原因是昆士兰州加工厂可收购的牛源供给减少。
澳大利亚多地持续降雨,所有州均有降水。新州中西部、西澳西南部雨量偏少且分布零散。
市场表现与上周相近,降雨促使养殖户压栏惜售。小牛与羔羊上栏量减少,供给收紧,带动行情指标走高。
肉牛市场
全国肉牛上栏量环比下降8%,至52233头。持续充沛的降雨改善饲草条件,养殖户选择压栏留牛。
本周所有肉牛品类行情指数全部上涨,涨幅区间为:育肥小母牛指数上涨1%,补栏一岁母牛指数上涨5%。昆州近一个月上栏量大幅回落,从9月的116873头降至10月的62933头。
加工母牛指数再创新高,达到活重407澳分/公斤。罗马牲畜交易市场的牛源占该指数统计样本的10%,市场报告称本次上市优质母牛品相出众。
育肥阉牛指数本周上涨3.6%,报活重547澳分/公斤,统计样本共6559头。该指数近一个月累计上涨11%,新州北部交易市场报价表现最强。
补栏一岁母牛指数创下所有肉牛指数中最大月度涨幅,上涨20%,报活重494澳分/公斤。供给收紧是主要原因:10月纳入该指数统计的牛只数量为13945头,9月为19413头。
绵羊市场
全国羔羊上栏量本周下降8%,至52233头;绵羊上栏量保持平稳,小幅上涨0.8%,达到84746头。除美利奴羔羊指数下跌0.8%至胴体重1089澳分/公斤外,其余所有品类指数均走高。
重羔羊指数本周上涨2.6%,报胴体重1159澳分/公斤,统计样本23190头。沃加沃加市场供货量占全国的33%,均价1175澳分/公斤。巴拉腊特与霍舍姆市场报价最优,两地均价均突破1200澳分/公斤。
补栏羔羊指数本周上涨2%,报胴体重1218澳分/公斤,统计样本32268头,该指数近一个月累计上涨10%。
新州牲畜市场反馈羔羊膘情品质参差不齐:沃加沃加表示,本季新羔羊当中相当一部分新鲜度欠佳,而亚斯市场的羔羊膘情状况良好。
屠宰量
统计周期:截至2026年10月23日当周
(1)牛只
全国肉牛屠宰量环比下降5%,至140062头。昆士兰州屠宰厂降幅居首,环比下跌10%,降雨导致牧场通行受阻,加工厂牛源供给紧张。
各州肉牛屠宰量(同比):
新南威尔士州:下降7%,33217头
昆士兰州:下降16%,70774头
南澳大利亚州:上涨2%,3904头
塔斯马尼亚州:上涨6%,4761头
维多利亚州:下降11%,23570头
西澳大利亚州:上涨6%,3836头
(2)羊肉
全国羔羊屠宰量环比下降2%,至394978头;全国绵羊屠宰量环比上升1%,至164861头。
各州羔羊屠宰量(同比):
新南威尔士州:下降6%,104820头
昆士兰州:下降12%,1083头
南澳大利亚州:下降28%,33114头
塔斯马尼亚州:上涨24%,8696头
维多利亚州:下降11%,194575头
西澳大利亚州:下降1%,52690头
内容供稿:澳大利亚肉类与畜牧业协会市场信息分析师 亚历克斯·弗莱
信息截至2026年10月30日发布时准确无误。
澳大利亚肉类与畜牧业协会(MLA)不对本刊物所载任何信息的准确性、完整性及时效性作出任何保证。用户使用或依赖本刊物任何内容,风险自行承担;因使用或依赖相关信息所造成的任何损失与损害,MLA概不承担任何责任。未经MLA事先书面许可,本刊物任何内容不得擅自转载、复制。凡使用MLA刊物、报告及相关信息,均须遵守MLA市场报告及信息使用条款。
消息来源:MLA
Weekly cattle and sheep market wrap
Key points
Rainfall continued across large parts of the country, encouraging producers to retain stock.
The Processor Cow Indicator continued to set new records.
Cattle slaughter declined, led by reduced stock access and availability for Queensland processors.
Rainfall continued across large parts of the country, with every state recording falls. Rain was lighter and more scattered across central and western NSW and south-west WA.
The market response was similar to last week with rainfall encouraging producers to retain stock. Smaller cattle and lamb yardings tightened supply and drove indicators higher.
Cattle market
The national cattle yarding declined 8% week-on-week to 52,233 head as producers continued to receive significant rainfall, which boosted feedbases and encouraged stock retention.
All cattle indicators lifted over the week with gains ranging from 1% for the Feeder Heifer Indicator to 5% for the Restocker Yearling Heifer Indicator. Queensland yardings have fallen significantly over the last month from 116,873 head in September to 62,933 head in October.
The Processor Cow Indicator moved further into record territory reaching 407¢/kg liveweight (lwt). Roma Saleyards accounted for 10% of cattle contributing to the indicator with the market report noting excellent quality across the prime cow offering.
The Feeder Steer Indicator lifted 3.6% over the week to 547¢/kg liveweight, across an offering of 6,559 head. The indicator has lifted 11% over the last month with northern NSW saleyards recording the strongest prices.
The Restocker Yearling Heifer Indicator recorded the strongest monthly increase of any cattle indicator, lifting 20% to 494¢/kg lwt. Tighter supply has been a major factor with 13,945 head contributing to the indicator in October, compared with 19,413 head in September.
Sheep market
The national lamb yarding dropped 8% over the week to 52,233 head, while the sheep yarding remained stable (lifting 0.8%) to 84,746 head. All indicators lifted except for the Merino Lamb Indicator, dropping 0.8% to 1,089¢/kg carcase weight (cwt).
The Heavy Lamb Indicator lifted 2.6% over the week to 1,159¢/kg cwt across an offering of 23,190 head. Wagga Wagga accounted for 33% of the national offering and averaged 1,175¢/kg cwt. The strongest prices were recorded at Ballarat and Horsham where both markets averaged more than 1,200¢/kg cwt.
The Restocker Lamb Indicator lifted 2% over the week to 1,218¢/kg cwt across an offering of 32,268 head. The indicator has climbed 10% over the past month.
NSW saleyard reports noted mixed quality and condition. Wagga Wagga reported a lack of freshness across a large proportion of its new-season lamb offering, while Yass noted good condition.
Slaughter
Week ending 23 October 2026
(1)Cattle
National cattle slaughter decreased 5% week-on-week to 140,062 head. Queensland processors led the decline with slaughter down 10% week-on-week as rainfall disrupted property access and limited stock availability for processors.
State-by-state cattle slaughter (YoY):
NSW: down 7% to 33,217 head
Queensland: down 16% to 70,774 head
SA: up 2% to 3,904 head
Tasmania: up 6% to 4,761 head
Victoria: down 11% to 23,570 head
WA: up 6% to 3,836 head.
(2)Sheep
National lamb slaughter decreased 2% week-on-week to 394,978 head, while national sheep slaughter increased 1% to 164,861 head.
State-by-state lamb slaughter (YoY):
NSW: down 6% to 104,820 head
Queensland: down 12% to 1,083 head
SA: down 28% to 33,114 head
Tasmania: up 24% to 8,696 head
Victoria: down 11% to 194,575 head
WA: down 1% to 52,690 head.
Attribute content to: Alex Fry, MLA Market Information Analyst
Information is correct at time of publication on 30 October 2026
MLA makes no representations as to the accuracy, completeness or currency of any information contained in this publication. Your use of, or reliance on, any content is entirely at your own risk and MLA accepts no liability for any losses or damages incurred by you as a result of that use or reliance. No part of this publication may be reproduced without the prior written consent of MLA. All use of MLA publications, reports and information is subject to MLA’s Market Report and Information Terms of Use.
Source:MLA

